Answer first/ 先说结论
A Malaysian factory sale does not automatically transfer every machine, production line, transformer, tank, rack, tool or spare part found on the premises.
马来西亚厂房买卖不会自动转让现场的每一台机器、生产线、变压器、储罐、货架、工具或备件。
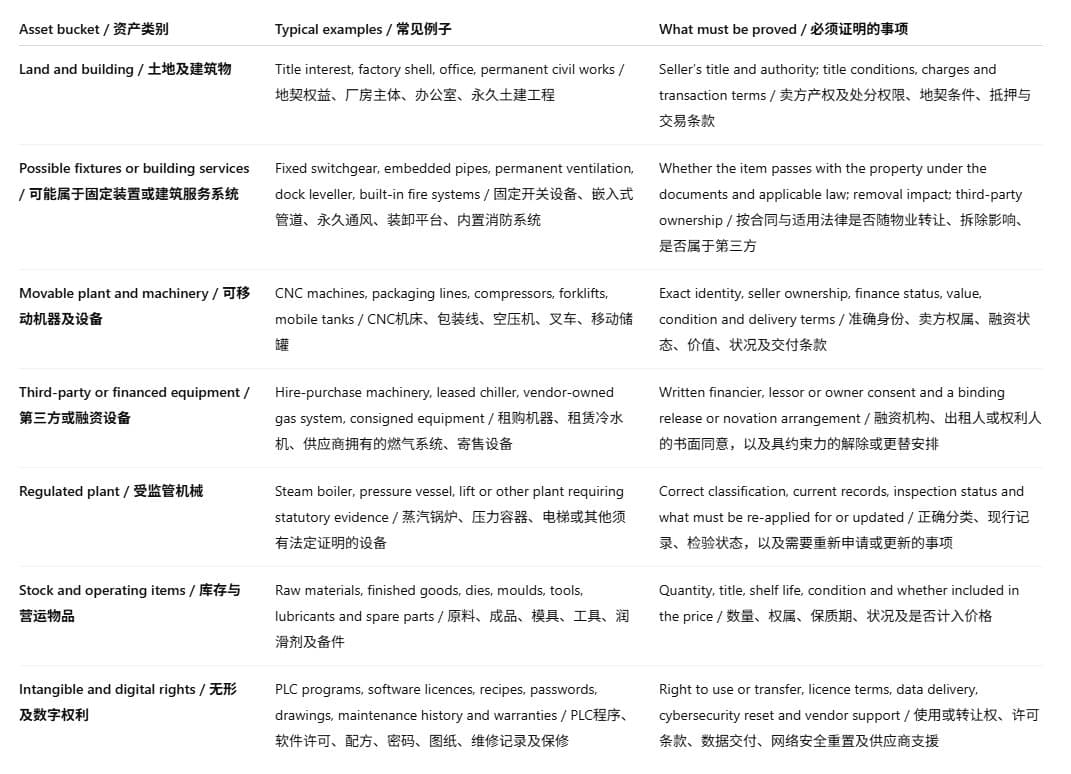
Before paying a deposit or fixing one aggregate price, the parties should identify each asset, decide whether it is part of the land and building, a fixture, movable plant, leased or financed equipment, regulated machinery, inventory or an intangible right, and then prove that the seller has authority to transfer it.
在支付订金或确定一笔总价前,双方应逐项识别资产,判断它属于土地建筑、固定装置、可移动机器、租赁或融资设备、受监管机械、库存还是无形权利,并证明卖方有权转让。
The safest structure is a controlled asset register attached to the letter of offer and sale agreement.
最稳妥的做法,是把一份受控资产清单附在要约书及买卖协议中。
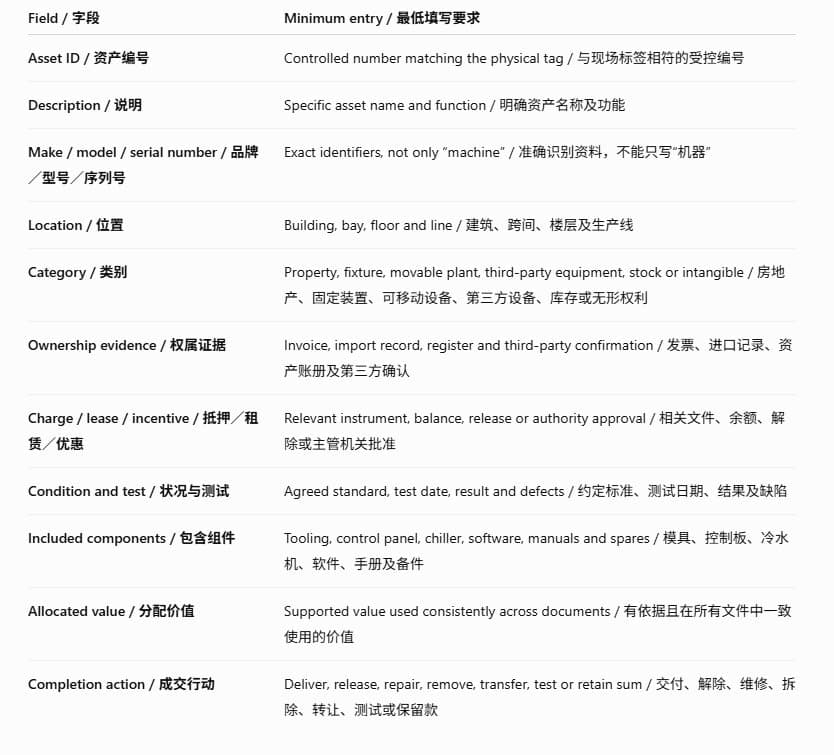
It should show the asset description, make, model, serial number, exact location, agreed category, ownership evidence, financing or charge status, regulatory documents, condition, allocated value, included accessories and the test or delivery required at handover.
清单应列出资产说明、品牌、型号、序列号、准确位置、约定类别、权属证据、融资或抵押状态、监管文件、设备状况、分配价值、所含配件,以及交接时必须完成的测试或交付。
Anything not expressly included should be treated as excluded until the documents say otherwise.
凡未明确列入的项目,在文件确认前均应视为不包括。
This article is a transaction and property due-diligence framework, not legal, tax, valuation or engineering advice.
本文提供的是交易与物业尽调框架,并非法律、税务、估值或工程意见。
The classification and tax treatment of a particular item depend on the facts and transaction documents; Malaysian legal, tax, valuation and technical advisers should confirm the final position.
每项资产的分类及税务处理取决于实际事实和交易文件,最终结论应由马来西亚法律、税务、估值及技术顾问确认
“Inside the factory” is not an asset category“放在厂房里”并不是资产类别
Whether a physical item is a fixture or movable property is not decided by size alone.
实体物品属于固定装置还是可移动资产,不能只看尺寸。
Attachment, purpose, removal consequences, ownership arrangements and the parties’ documents can all matter.
固定方式、用途、拆除后果、权属安排及双方文件都可能影响结论。
Do not rely on labels such as “built-in”, “permanent” or “included”.
不要只依赖“内置”“永久”或“包括”等标签。
Require the transaction lawyer to resolve the classification and draft the agreement accordingly.
应由交易律师确认分类,并据此起草协议。
The 12 checks before committing承诺交易前的12项检查
1. Define exactly what transaction is taking place 先定义交易到底包括什么
Is the buyer acquiring only the real property, real property plus selected machinery, all operating assets, a going concern, or shares in the company that owns the factory and equipment?
买方购买的是纯房地产、房地产加指定机器、全部营运资产、持续经营业务,还是持有厂房与设备的公司股份?
Those structures transfer different rights and liabilities.
不同结构会转移不同的权利及责任。
A property SPA with a vague sentence saying “machinery included” is not a substitute for an asset purchase agreement, a share-sale review or a detailed schedule.
一份只笼统写着“包括机器”的物业买卖协议,不能取代资产收购协议、股权交易审查或详细附表。
State whether the price includes dismantling, recommissioning, stock, consumables, intellectual property, customer orders, employees or liabilities.
文件应说明价格是否包括拆卸、重新调试、库存、耗材、知识产权、客户订单、员工或负债。
These items should not be allowed to drift into the deal through assumptions.
这些项目不能靠默契或假设自动进入交易。
2. Freeze a serial-numbered asset register 固定一份带序列号的资产清单
Walk the site with the seller, engineer and transaction team.
由卖方、工程师及交易团队共同巡查现场。
Photograph each material asset and record its make, model, serial number, capacity, year, exact bay, accessories and visible condition.
为每项重要资产拍照,并记录品牌、型号、序列号、容量、年份、准确位置、配件及可见状况。
Mark it physically with a controlled asset number.
再以受控资产编号在现场标识。
Reconcile the list with the seller’s fixed-asset register, invoices, maintenance records and financial statements.
清单应与卖方固定资产账册、发票、维修记录及财务报表相互核对。
Use four clear outcomes: included, excluded, to be removed before completion, or subject to a stated condition.
每项资产应明确归入四种结果:包括、不包括、成交前拆走,或须满足指定条件。
For production lines, list the main machine and every feeder, conveyor, controller, mould, jig, chiller, dust collector and software component required for it to work.
对于生产线,不只列主机,还要列出正常运作所需的送料机、输送带、控制器、模具、夹具、冷水机、除尘器及软件组件。
3. Separate property, fixtures and movable equipment 区分房地产、固定装置及可移动设备
Prepare a classification schedule instead of one undivided list.
应制作分类表,而不是一份不分性质的总清单。
For every disputed item, record how it is attached, why it was installed, whether removal damages the building or item, whether it serves the building generally or one production process, and what the title, lease, finance and installation documents say.
对每项有争议的物品,记录其固定方式、安装目的、拆除是否损坏建筑或物品、它服务整栋建筑还是某一生产工艺,以及地契、租约、融资及安装文件如何表述。
Examples requiring careful treatment include transformers, solar systems, gas skids, tanks, compressors, dock equipment, cleanroom panels, cold-room systems, racks and overhead cranes.
需要特别审查的例子包括变压器、太阳能系统、燃气撬装设备、储罐、空压机、装卸设备、洁净室板材、冷库系统、货架及天车。
A commercial description is not a legal conclusion.
商业名称并不是法律结论。
4. Prove that the seller owns every included item 证明卖方拥有每一项列入资产
Ask for acquisition invoices, import documents, payment evidence, fixed-asset records and supplier correspondence.
应取得采购发票、进口文件、付款证明、固定资产记录及供应商往来资料。
Compare the seller’s legal name, asset description and serial number.
并核对卖方法定名称、资产说明及序列号。
An asset may be used by the seller but owned by a related company, landlord, financier, utility, equipment vendor or customer.
卖方可能正在使用设备,但真正权利人可能是关联公司、业主、融资机构、公用事业公司、设备供应商或客户。
For hire-purchase, leasing, retention-of-title, consignment or vendor-supplied equipment, obtain the underlying agreement and a direct confirmation from the third party.
对于租购、租赁、所有权保留、寄售或供应商提供的设备,应取得原始协议及第三方直接确认。
A seller’s warranty is useful, but it should not replace documentary proof and an effective release.
卖方保证有价值,但不能取代文件证据及有效解除。
5. Search company charges and obtain a lender release 查询公司抵押并取得融资机构解除
Sections 352 and 353 of Malaysia’s Companies Act 2016 address registration of specified charges, including a floating charge over a company’s undertaking or property.
马来西亚《2016年公司法令》第352及353条涉及指定抵押的登记,包括对公司业务或财产设立的浮动抵押。
Section 360 provides for satisfaction and release of property from a registered charge, supported by sufficient evidence.
第360条规定已登记抵押的清偿及财产解除,并须提交充分证据。
Obtain the company search, the actual security instruments, the lender’s redemption or release terms and completion evidence.
应取得公司查询、实际担保文件、融资机构赎回或解除条件,以及成交证明。
An SSM search is an important screen, but it is not complete proof that no other ownership, hire-purchase, retention-of-title or contractual restriction exists.
SSM查询是重要筛选工具,但不能完整证明不存在其他权属、租购、所有权保留或合同限制。
6. Check Customs, LMW and incentive conditions 核对海关、LMW及投资优惠条件
If the seller operates a Licensed Manufacturing Warehouse (LMW/GPB), do not assume imported machinery can simply be sold or removed.
如果卖方经营海关持牌制造仓库(LMW/GPB),不能假设进口机器可以直接出售或移走。
Royal Malaysian Customs states that machinery and equipment may not be disposed of or removed from GPB premises without approval.
马来西亚皇家关税局说明,未经批准,不得处置或移出GPB场所内的机器设备。
Its page, last updated on 23 February 2026, also explains that import duty and sales tax may be payable for equipment under ten years old where applicable, while approval remains required even for equipment over ten years old.
该页面于2026年2月23日更新,并说明使用期少于十年的设备在适用情况下可能须缴进口税及销售税;超过十年的设备即使获免税,处置仍须批准。
Also check whether any machinery was imported or acquired under an investment incentive, exemption, grant or approved project condition.
还应核实机器是否依据投资优惠、免税、补助或获批项目条件进口或购买。
Require the seller to identify the approval letter, responsible authority, remaining conditions and the written consent or repayment treatment before completion.
成交前,应要求卖方说明批准函、主管机关、尚未履行的条件,以及书面同意或补缴安排。
7. Allocate the purchase price fairly and supportably 公平且有依据地分配交易价格
Do not use one unexplained number for land, buildings, machinery, stock and intangible rights.
不要用一个无法解释的数字同时涵盖土地、建筑、机器、库存及无形权利。
Obtain appropriate property and machinery valuations and agree an allocation that the legal, tax and accounting documents use consistently.
应取得适当的房地产及机器设备估值,并商定一个在法律、税务及会计文件中一致使用的价格分配。
IRBM Public Ruling No. 7/2017 states that when plant or machinery is disposed of with other assets for one aggregate sum, the sale price must be allocated fairly and reasonably.
内陆税收局第7/2017号公共裁定说明,当机器设备与其他资产以一笔总价处置时,售价必须在各项资产之间公平、合理地分配。
An unreasonable allocation may be revised even when separate prices were agreed.
即使双方已同意分项价格,不合理的分配仍可能被调整。
The ruling also explains that plant or machinery disposal can create a balancing allowance or balancing charge.
该裁定也解释,处置机器设备可能产生平衡免税额或平衡课税额。
IRBM separately explains that RPGT applies to gains from disposal of Malaysian chargeable assets such as commercial buildings and land.
内陆税收局另行说明,房地产收益税适用于处置马来西亚应课税资产所得的收益,例如商业建筑及土地。
The parties should obtain transaction-specific advice on RPGT, income tax, capital allowances, stamp duty, sales tax, service tax and invoice treatment instead of applying the real-property answer automatically to machinery.
双方应就房地产收益税、所得税、资本免税额、印花税、销售税、服务税及发票处理取得针对本交易的意见,而不能把房地产的税务结论自动套用到机器设备。
8. Verify regulatory status—without assuming it transfers 核实监管状态——不能假设证书自动转移
Identify every boiler, pressure vessel, lift and other regulated plant.
应识别每台锅炉、压力容器、电梯及其他受监管机械。
Match the exact equipment to its design, registration, inspection, certificate, competent-person and maintenance records.
并把准确设备与其设计、登记、检验、合格证、合资格人员及维修记录相匹配。
Malaysia’s Occupational Safety and Health (Plant Requiring Certificate of Fitness) Regulations 2024 govern relevant plant and came into operation on 1 June 2024.
马来西亚《2024年职业安全与健康(须取得合格证书的机械)条例》规管相关设备,并于2024年6月1日生效。
A certificate in the seller’s file does not by itself prove that the buyer can operate the equipment after a change of occupier, process, layout, fuel, installation or responsible party.
卖方档案中的证书,并不能单独证明买方在使用者、工艺、布局、燃料、安装位置或责任主体改变后仍可操作该设备。
Obtain written technical and regulatory confirmation for the actual post-completion arrangement.
应针对成交后的实际安排取得书面技术及监管确认。
9. Test condition, capacity and production performance 测试设备状况、容量及生产表现
An idle machine can look clean while hiding obsolete controls, unavailable parts, damaged tooling, poor accuracy or unstable output.
闲置机器外观看来可能很整洁,但可能隐藏控制系统过时、备件停产、模具损坏、精度不足或产量不稳定等问题。
Agree a test protocol before signing or make satisfactory testing a condition precedent.
应在签约前商定测试方案,或把测试合格列为先决条件。
Where practical, run representative materials at an agreed speed, duration, quality and yield, and record energy use, alarms, rejects, vibration, temperature and leakage.
在可行情况下,使用代表性物料,以约定速度、时间、质量及良率试产,并记录能耗、警报、不良品、振动、温度及泄漏。
State whether the sale is “as is, where is”, subject to disclosed defects, or warranted to meet defined acceptance criteria.
合同应说明设备是按“现状及所在地”出售、受已披露缺陷限制,还是保证达到明确验收标准。
The expression “working condition” is too vague unless the documents say what it means and what happens if the machine fails.
“可正常运作”如果没有定义测试方法及失败后果,就过于模糊。
10. Test the factory–machine interface 测试厂房与机器之间的接口
The buyer is not only buying machines; it may be inheriting foundations, pits, exhaust, chilled water, compressed air, gas, power quality, earthing, drainage, fire protection, network links and environmental controls.
买方购买的不只是机器,还可能接收基础、地坑、排气、冷冻水、压缩空气、燃气、电能质量、接地、排水、消防、网络连接及环境控制。
Reconcile equipment demand with the building’s approved and available capacity.
应把设备需求与厂房的核准及实际可用容量逐项核对。
Document which connections remain, who owns them, their tested capacity and who repairs damage if an excluded machine is removed.
应记录哪些连接系统保留、由谁拥有、测试容量为何,以及拆走不包括的机器造成损坏时由谁修复。
A production line without its chiller, transformer, exhaust treatment or software may have little operating value.
缺少冷水机、变压器、废气处理或软件的生产线,营运价值可能非常有限。
11. Secure the digital, service and knowledge package 确保数字、服务及知识资料完整交付
List PLC and HMI backups, passwords, software licences, remote-access accounts, recipes, calibration data, manuals, drawings, spare-parts lists, maintenance history, warranty rights and vendor contacts.
列明PLC及HMI备份、密码、软件许可、远程访问账户、配方、校准资料、手册、图纸、备件清单、维修历史、保修权利及供应商联系人。
Confirm whether licences and warranties can be assigned and whether the original supplier will support the buyer.
确认许可及保修能否转让,以及原供应商是否继续支援买方。
Require the seller to remove its data, close remote access and deliver a clean administrator handover without destroying operational history needed by the buyer.
卖方应清除其资料、关闭原有远程访问,并完成干净的管理员权限交接,同时不得删除买方需要的营运历史。
Cybersecurity and intellectual-property obligations should be written, not improvised on completion day.
网络安全及知识产权责任必须写入文件,不能在成交日临时决定。
12. Turn the handover into a controlled completion process 把交接变成受控的成交程序
Attach the final asset register, photographs, condition report and valuation schedule to the transaction documents.
把最终资产清单、照片、状况报告及估值表附入交易文件。
State when title and risk pass, which releases and approvals are completion deliverables, who insures the assets, what may be removed, how damage is repaired, and what remedy applies for missing, substituted or failed equipment.
明确权属与风险何时转移、哪些解除和批准属于成交交付文件、由谁投保、哪些物品可拆走、损坏如何修复,以及资产缺失、被替换或测试失败时采取什么补救。
Repeat the serial-number walk-through immediately before completion.
成交前应再次按序列号巡查。
Record meter readings, keys, passwords, manuals, spares and live test results.
并记录仪表读数、钥匙、密码、手册、备件及现场测试结果。
Use a signed handover certificate with unresolved items, retention sums or escrow where appropriate.
使用双方签署的交接证书列出未解决事项,并在适当情况下采用保留款或托管安排。
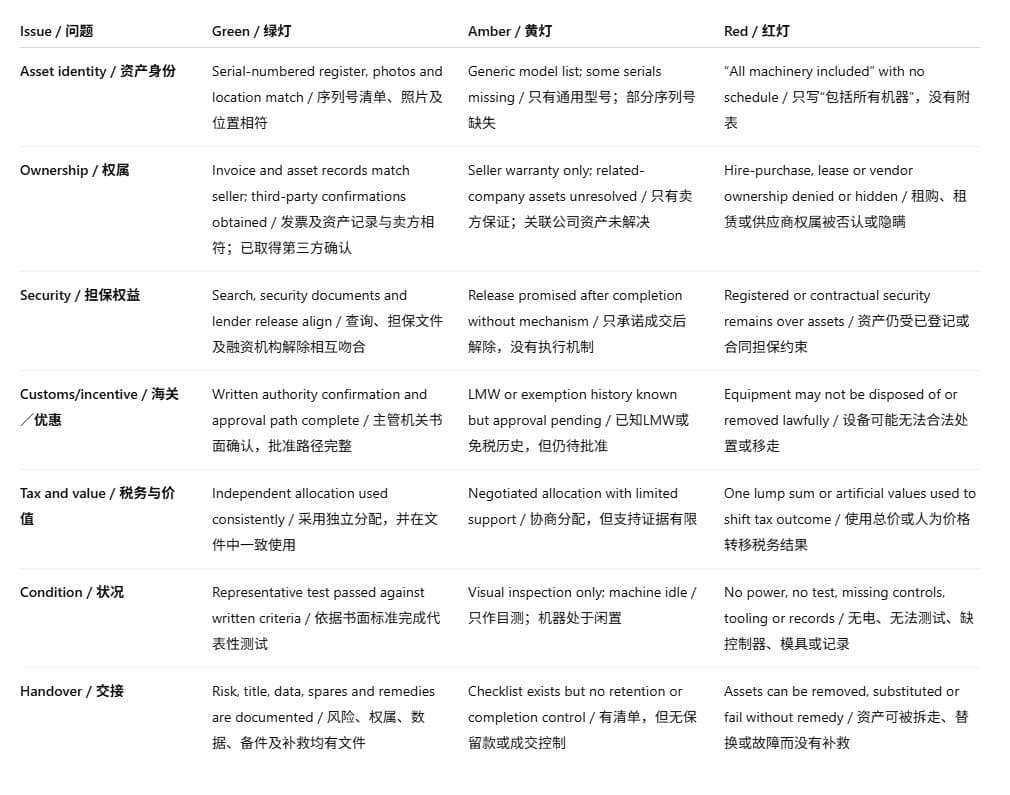
Evidence matrix: green, amber or red?证据矩阵:绿灯、黄灯还是红灯?
A practical asset schedule实用资产附表格式
Example: why one price is not enough示例:为什么一笔总价不够
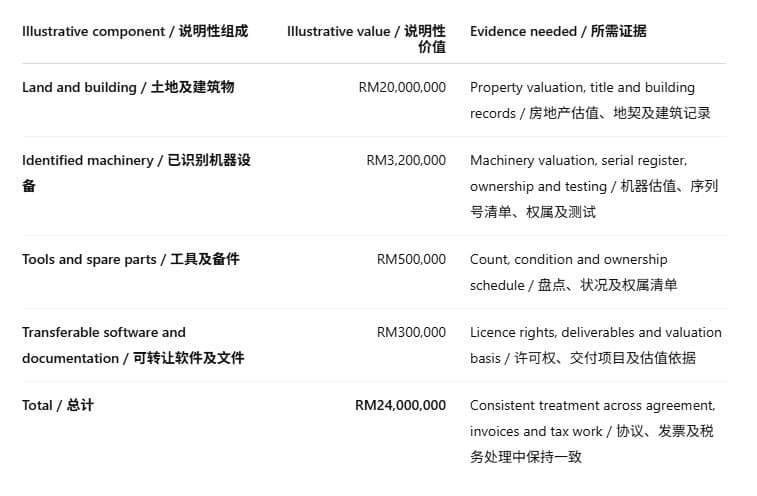
Assume the parties discuss RM24 million for a factory “with machinery”.
假设双方讨论一宗总价RM2,400万的“厂房连机器”交易。
The transaction team should not simply insert RM24 million as an undivided figure.
交易团队不应只把RM2,400万作为不可分割的数字写入文件。
A property valuer, machinery valuer, tax adviser and lawyer may need to support a schedule such as land and building, specific fixtures, identified movable machinery, stock and separately transferable software rights.
房地产估价师、机器估价师、税务顾问及律师可能需要共同支持一份分项表,例如土地建筑、指定固定装置、已识别可移动机器、库存及可单独转让的软件权利。
The figures below are illustrative only, not a valuation or tax answer.
以下数字只作说明,并非估值或税务结论。
Recommended transaction sequence建议交易流程
Define the transaction perimeter and post-completion operating plan.
定义交易范围及成交后的营运计划。
Freeze the serial-numbered asset register and exclusions list.
固定带序列号的资产清单及排除清单。
Complete title, corporate, finance, Customs, incentive, regulatory, tax and technical reviews.
完成产权、公司、融资、海关、优惠、监管、税务及技术审查。
Obtain separate property and machinery valuation support.
取得房地产与机器设备的独立估值支持。
Agree the test protocol and run representative acceptance tests.
商定测试方案,并完成代表性验收测试。
Draft conditions precedent for ownership, lender release, authority approval and document delivery.
为权属、融资解除、主管机关批准及文件交付设置先决条件。
Repeat the asset count and test immediately before completion.
成交前再次盘点并测试资产。
Sign a controlled handover certificate and retain money for unresolved deliverables where appropriate.
签署受控交接证书,并在适当情况下为未完成事项保留款项。
Frequently Asked Questions常见问题
1. If the listing says “factory with machinery”, are all machines included? 如果广告写着“厂房连机器”,是否所有机器都包括?
No. 不是。
The listing is marketing information, not a complete transfer instrument.
广告属于营销资料,并不是完整的转让文件。
Only a precise, signed asset schedule and transaction documents can establish what is included, excluded or subject to conditions.
只有准确并经签署的资产清单及交易文件,才能确定哪些资产包括、排除或附带条件。
2. Does a machine bolted to the floor automatically belong to the building? 机器以螺栓固定在地面,就自动属于建筑物吗?
Not automatically. 不会自动归入。
Attachment is relevant, but purpose, removal consequences, ownership documents, financing and applicable law may also matter.
固定方式很重要,但安装目的、拆除后果、权属文件、融资及适用法律也可能影响结论。
Ask the transaction lawyer to classify the item and draft the documents expressly.
应由交易律师确认分类,并在文件中明确处理。
3. Is the seller’s fixed-asset register enough proof of ownership? 卖方的固定资产账册足以证明权属吗?
No. 不足。
Reconcile it with invoices, payment and import records, physical serial numbers, finance agreements and third-party confirmations.
还应与发票、付款及进口记录、现场序列号、融资协议及第三方确认相互核对。
Accounting recognition and legal ownership are related but not identical questions.
会计确认与法律权属有关联,但并不是同一个问题。
4. Can machinery be sold while a company charge remains registered? 公司抵押仍然登记时,可以出售机器吗?
The actual security instrument and lender rights must be reviewed.
必须审查实际担保文件及融资机构权利。
If the asset falls within the security, obtain the lender’s binding release or agreed completion mechanism.
如果资产落入担保范围,应取得具约束力的解除,或约定成交机制。
Do not rely only on a promise that the charge will be dealt with later.
不要只依赖“之后会处理抵押”的承诺。
5. Can equipment inside an LMW be transferred with the factory? LMW内的设备能随厂房一起转让吗?
Not without checking the Customs position.
不能在未核实海关要求的情况下直接转让。
Current Customs guidance states that machinery and equipment may not be disposed of or removed from GPB premises without approval, and duty or tax may apply depending on the facts and age of the equipment.
现行海关指引说明,未经批准,不得处置或移出GPB场所内的机器设备;是否须缴税取决于实际情况及设备年限。
6. Should land and machinery have separate values? 土地与机器是否应分别估值?
Usually the transaction team should establish a fair and supportable allocation.
通常交易团队应建立公平且有依据的分配。
IRBM Public Ruling No. 7/2017 says an aggregate price for plant or machinery sold with other assets must be allocated fairly and reasonably.
内陆税收局第7/2017号公共裁定说明,机器设备与其他资产以总价出售时,必须公平合理地分配价格。
Obtain professional valuation and tax advice.
应取得专业估值及税务意见。
7. Does a valid machine certificate automatically transfer to the buyer? 有效机器证书会自动转给买方吗?
Do not assume so. 不要这样假设。
Match the certificate to the exact machine and confirm the effect of any change in occupier, responsible party, location, layout, installation or use with the relevant authority and competent professional.
应把证书与准确设备相匹配,并由相关主管机关及合资格专业人士确认使用者、责任主体、地点、布局、安装或用途改变后的影响。
8. What is the single most important completion document? 成交时最重要的单一文件是什么?
There is no single substitute for the evidence set, but the controlled handover certificate is critical.
没有任何单一文件能够取代整套证据,但受控交接证书非常关键。
It should attach the final serial-numbered register, test results, releases, approvals, keys, passwords, manuals, spares and unresolved items.
它应附上最终序列号清单、测试结果、解除文件、批准、钥匙、密码、手册、备件及未解决事项。
Final decision rule最终决策规则
Do not value a “factory with machinery” until the property, asset and evidence boundaries are clear.
在房地产、资产及证据边界未厘清前,不要为“厂房连机器”整体定价。
If the seller cannot prove identity, ownership, release, authority approval, condition and deliverability for an included asset, price it as an unresolved risk—not as productive capacity already acquired.
如果卖方无法证明某项列入资产的身份、权属、解除、主管机关批准、状况及可交付性,就应把它计为未解决风险,而不是已经取得的生产能力。
For Malaysian and China-based transaction teams, one bilingual asset register should become the common control document used by headquarters, local management, lawyers, valuers, tax advisers, engineers, financiers and the seller.
对于马来西亚及中国交易团队,应以同一份双语资产清单作为总部、本地管理层、律师、估价师、税务顾问、工程师、融资机构及卖方的共同控制文件。
That single source of truth prevents a translation gap from becoming an ownership or completion dispute.
统一事实来源,能够避免翻译差异演变成权属或交接争议。